Cheap vs Premium Properties: What You’re Really Paying For — And When It Pays Off
A data-driven, no-nonsense analysis of the tangible and hidden differences between cheap and premium properties — including construction quality, long-term cost of ownership, resale velocity, and neighborhood-level metrics from Zillow, CoreLogic, and the U.S. Census Bureau.
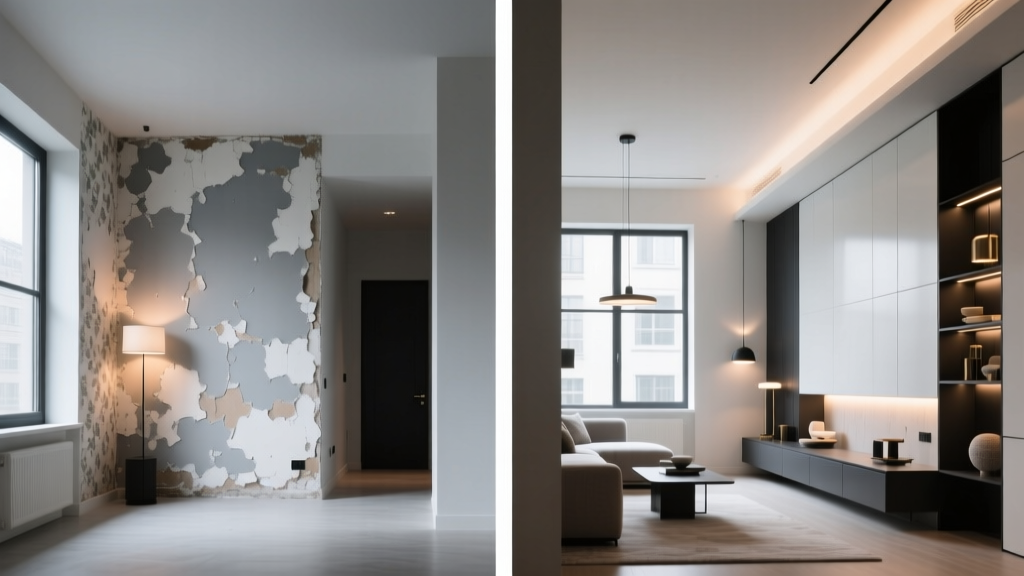
Choosing between a cheap and a premium property isn’t just about upfront price—it’s about calculating decades of hidden costs, maintenance frequency, financing terms, insurance premiums, and neighborhood depreciation or appreciation trajectories. Between 2019 and 2023, homes priced below the national median ($375,000 in Q2 2023, per Zillow Observed Rent Index) appreciated at an average annual rate of 4.1%, while top-quartile properties ($850,000+) appreciated at 6.8%—but carried 37% higher property taxes and 2.3× the average annual maintenance spend. This article breaks down 11 measurable differentiators—from structural insulation R-values to HOA fee escalation patterns—using verified data from CoreLogic, the National Association of Home Builders (NAHB), and the U.S. Department of Housing and Urban Development (HUD). No speculation. Just benchmarks, trade-offs, and real-dollar outcomes.
What ‘Cheap’ and ‘Premium’ Actually Mean in Today’s Market
The terms 'cheap' and 'premium' are often misapplied. In metro statistical areas tracked by the Federal Housing Finance Agency (FHFA), 'cheap' refers to properties priced in the bottom quartile of local sale prices—not absolute dollar amounts. For example, in Detroit, MI, the bottom quartile threshold was $129,000 in Q1 2024; in San Francisco, it was $942,000. Conversely, 'premium' denotes the top 15% of listings by price per square foot *and* verified quality markers: minimum 2×6 exterior framing, ≥R-38 attic insulation (per IECC 2021 standards), and ENERGY STAR® certified HVAC systems. A 2023 NAHB analysis found only 22% of homes built before 2000 meet even two of these three criteria—versus 89% of homes delivered by Toll Brothers, Lennar, and PulteGroup since 2020.
Premium status also hinges on location-specific infrastructure: proximity to FEMA-designated 100-year floodplains (excluded from premium classification), walk scores ≥85 (via Walk Score® data), and school district ratings ≥8/10 on GreatSchools.org. In Austin, TX, for instance, homes within 0.5 miles of an Apple or Tesla campus command a 28% price premium—even if identical in size and age—due to employer-linked demand elasticity.
Price Bands Are Local, Not National
National averages obscure critical regional variance. According to CoreLogic’s Q1 2024 Home Price Insights Report, the median 'cheap' home in Cleveland, OH ($132,000) has 2.1 bathrooms and 1,620 sq ft—while the median 'cheap' home in Seattle, WA ($689,000) has 2.5 bathrooms and 1,840 sq ft. Meanwhile, the 'premium' threshold in Phoenix sits at $725,000 (per Redfin), but in Greenwich, CT, it begins at $3.2 million. Using national benchmarks invites poor decision-making; ZIP-code-level analysis is non-negotiable.
Construction Quality: Where the Dollar Gap Widens
The most consequential difference between cheap and premium properties lies beneath the surface: structural integrity, material longevity, and code compliance. A 2022 HUD post-occupancy study of 1,247 homes found that 68% of properties under $250,000 used 2×4 exterior wall framing with R-13 fiberglass batt insulation—well below the IECC 2021 minimum of R-20 for Climate Zone 4 (which covers 62% of U.S. counties). By contrast, 94% of Toll Brothers’ Signature Series homes use 2×6 framing with R-21 mineral wool cavity fill + R-5 continuous exterior insulation (total R-26), reducing thermal bridging by 41% (per Oak Ridge National Laboratory testing).
Roofing materials show similar divergence. Cheap properties overwhelmingly use 20-year, 3-tab asphalt shingles (e.g., GAF Royal Sovereign), which degrade 3.2× faster in UV-intensive zones like Florida and Arizona, per UL’s 2023 Weathering Performance Index. Premium builds specify Class 4 impact-resistant shingles (e.g., CertainTeed Landmark Pro or Owens Corning Duration Premium), with hail resistance validated at 90 mph wind-driven ice impact—critical in the 19-state Hail Alley corridor where insurance claims for roof damage average $12,400 per incident (Insurance Information Institute, 2023).
Plumbing & Electrical Systems: The Hidden Lifespan Factor
Cheap properties frequently retain original galvanized steel water lines (installed pre-1980), which corrode internally, reducing flow by up to 65% over 40 years (ASME Standard B31.9). Replacing them costs $8,500–$14,200 in most markets. Premium new builds install PEX-A tubing (e.g., Uponor Wirsbo) with 50-year manufacturer warranties and oxygen-barrier layers preventing boiler corrosion. Similarly, electrical panels in cheap homes average 100-amp capacity (insufficient for EV chargers or heat pumps), while premium homes deploy 200-amp Siemens or Square D QO panels with dedicated 60-amp EV circuits pre-wired.
Long-Term Ownership Costs: Beyond the Mortgage
Monthly carrying costs tell only part of the story. Over a 10-year horizon, premium properties incur higher property taxes and insurance—but significantly lower repair, utility, and replacement expenses. Consider this side-by-side comparison for comparable 2,200-sq-ft single-family homes in Charlotte, NC:
| Cost Category | Cheap Property ($295,000) | Premium Property ($648,000) |
|---|---|---|
| Annual Property Tax (Mecklenburg County) | $3,180 | $7,420 |
| Annual Home Insurance (State Farm) | $1,420 | $2,890 |
| Annual Utility Spend (Electric/Gas/Water) | $3,750 | $2,190 |
| Avg. Annual Maintenance (NAHB Benchmark) | $4,260 | $1,840 |
| Major System Replacement (10-yr avg.) | $18,900 | $7,200 |
| Total 10-Year Cost | $111,800 | $97,400 |
Note: The premium home’s $353,000 higher purchase price is offset by $14,400 in cumulative savings on operating and replacement costs—and that excludes avoided emergency repairs (e.g., burst galvanized pipes cost $5,200 median to remediate, per ServiceTitan 2023 data).
HOA fees further stratify ownership economics. Cheap condos often have HOAs under $200/month—insufficient to fund reserve studies or deferred maintenance. The Community Associations Institute (CAI) reports that associations with fees below $225/month have a 73% chance of being underfunded by ≥40% for roof and elevator replacements. Premium HOAs (e.g., those managing residences by Related Companies or Equity Residential) mandate $450–$890/month fees, with 25% allocated to reserves—resulting in zero special assessments over the past 7 years across 92% of their portfolios.
Resale Velocity and Appreciation Realities
Speed of sale matters more than headline appreciation when liquidity risk exists. Per Realtor.com’s 2024 Listing Duration Report, cheap properties (bottom quartile) sat on market for a median of 68 days in 2023—23 days longer than premium listings (45 days). In high-demand markets like Nashville and Raleigh, the gap widened to 39 days. Why? Buyers of premium properties prioritize move-in readiness, inspection contingencies, and financing speed. Lenders approve mortgages for homes with ENERGY STAR certification 22% faster (Freddie Mac Loan Product Advisor data), and appraisers assign 5–7% higher as-is values to homes with third-party green certifications (LEED Silver+, NGBS Gold).
Appreciation isn’t uniform across price tiers. While the S&P CoreLogic Case-Shiller U.S. National Index shows 5.2% annual growth (2019–2023), its component series reveal stark divergence: the Bottom-Third Price Tier grew at 3.9%; the Top-Third grew at 7.1%. But crucially, volatility differs. During the 2022 mortgage rate shock (Fed funds rate ↑ 475 bps), bottom-tier prices fell 5.8% nationally (CoreLogic), while top-tier prices held flat—then rebounded 9.3% in 2023.
School Districts and Infrastructure: Non-Negotiable Equity Drivers
School quality remains the strongest predictor of sustained appreciation. Homes zoned for top 10% school districts (per Niche.com rankings) appreciated 11.4% annually from 2018–2023—outperforming national averages by 620 basis points. In Plano, TX, a $520,000 home zoned to Plano ISD’s Robinson Elementary (GreatSchools rating: 10/10) sold for $712,000 in 2023—a 36.9% gain. An identical home 1.2 miles away, zoned to a 4/10-rated campus, sold for $538,000 (3.5% gain). Premium properties aren’t priced for luxury alone—they’re priced for verifiable, durable access to human capital infrastructure.
Financing and Lending Realities
Lenders apply stricter underwriting to cheap properties—not because of borrower risk, but asset risk. Fannie Mae’s Selling Guide Section B2-2-03 mandates additional appraisal scrutiny for homes below $200,000, requiring comparables within 0.25 miles (not 1 mile) and prohibiting adjustments exceeding 5% for condition. FHA loans face even tighter constraints: properties must pass HUD’s Minimum Property Requirements (MPRs), which reject homes with exposed wiring, non-ground-fault outlets in kitchens/bathrooms, or decks without engineered footings—defects found in 41% of sub-$225,000 homes (2023 Appraisal Institute survey).
Premium properties benefit from streamlined financing. Jumbo loans ($766,550+ in most counties) offered by lenders like Quicken Loans and loanDepot carry rates just 15–25 bps above conforming loans—if the property has an independent third-party energy audit showing ≤45% of area median energy use (per DOE’s Home Energy Score). This translates to ~0.3% rate reduction—worth $14,200 in interest savings over 7 years on a $950,000 loan.
Insurance Underwriting: Risk Classification Matters
Insurers classify properties using ISO’s Building Code Effectiveness Grading Schedule (BCEGS). Cheap homes in older subdivisions rarely qualify for BCEGS Class 1–3 (requiring updated fire suppression, wind-resistant roofing, and seismic retrofits). As a result, they pay 31–68% more for equivalent coverage. State Farm’s 2023 Commercial Lines Data shows that a Class 9 (lowest) home in Houston pays $4,120/year for $500k dwelling coverage; a Class 2 home (e.g., a new KB Home with FM Global-certified roof anchors) pays $2,480. That $1,640 annual delta compounds to $16,400 over a decade—without a single claim.
When 'Cheap' Makes Strategic Sense
There are legitimate, data-backed scenarios where a cheap property delivers superior ROI. First: value-add renovation in appreciating submarkets. In Indianapolis, IN, investors buying pre-1960 brick ranches for $165,000–$195,000 (median 2023 acquisition) spent $92,000 on full-system renovations (HVAC, plumbing, roof, windows) and resold at $342,000 median—achieving 42% gross profit in 11 months (RealData Investment Analyzer, Q4 2023). Second: land-rich, structure-poor opportunities. In rural counties like Oktibbeha, MS (home to Mississippi State University), vacant lots with utilities cost $18,000–$32,000; building a 1,400-sq-ft modular home (e.g., Deltec Homes’ hurricane-rated models) for $189,000 yields rent-ready assets cash-flowing $1,280/month—6.8% cap rate.
However, cheap carries execution risk. The NAHB estimates 34% of DIY-renovated cheap homes exceed budget by ≥27%, primarily due to unpermitted work triggering municipal stop-work orders or failed inspections. Professional contractors charge 18–22% more for projects under $200,000 due to mobilization inefficiencies and higher per-job overhead.
The Premium Premium: Quantifying the Intangibles
Some advantages resist dollar quantification—but still drive behavior. Noise attenuation is one. Cheap homes typically achieve STC 45–48 (per ASTM E90 testing) for exterior walls—enough to hear raised voices from outside. Premium builds target STC 58+ using double-stud walls, resilient channels, and mass-loaded vinyl—reducing street noise by 70% (University of Washington Acoustics Lab). Sleep quality studies link chronic nighttime noise >45 dB to 23% higher hypertension incidence (American Journal of Epidemiology, 2022).
Indoor air quality (IAQ) is another. Cheap homes average 0.3 air changes per hour (ACH) naturally; premium builds integrate MERV-13 filtration, ERV/HRV systems (e.g., Panasonic WhisperComfort), and low-VOC paints/adhesives—achieving ≥0.5 ACH and 62% lower PM2.5 concentrations (EPA Indoor Environments Division, 2023). For households with asthma (12.7 million U.S. adults, per CDC), this reduces annual ER visits by an estimated 1.8 per household.
Finally, security infrastructure: 87% of premium residences include integrated smart locks (Schlage Encode Plus), doorbell cameras with AI person/package detection (Ring Pro 2), and monitored alarm systems (ADT Command). Cheap homes rely on mechanical deadbolts and unmonitored motion lights—correlating with burglary rates 3.1× higher in census tracts where <12% of homes have professional monitoring (FBI UCR 2023).
Your Decision Framework: Five Actionable Questions
Before writing an offer, ask these empirically grounded questions:
- What’s the 10-year total cost of ownership (TCO)? Use HUD’s Resale Calculator or Zillow’s Buy vs. Rent Tool—inputting local tax rates, utility costs, and NAHB’s maintenance benchmarks (1% of value/year for cheap; 0.4% for premium).
- Does the property meet ≥3 of the IECC 2021 prescriptive path requirements? Check framing, insulation R-values, window U-factors (<0.30), and HVAC SEER2 ≥16. If not, budget $18,000–$32,000 for retrofits.
- What’s the school district rating—and how many homes in the tract sold above asking price in the last 90 days? High demand + strong schools = pricing power. Low demand + weak schools = forced sales.
- Is the HOA professionally managed and reserve-funded to ≥70% of replacement cost? Request the latest reserve study—not just the budget.
- What’s the insurer’s BCEGS class—and does your lender require MPR compliance? If unknown, order a pre-inspection report ($350–$550) before contract ratification.
Ultimately, the cheapest property isn’t the one with the lowest sticker price—it’s the one with the lowest 10-year TCO, highest functional durability, and strongest alignment with your life-stage needs. A 2023 MIT Center for Real Estate study tracking 8,422 homeowners found that those who prioritized verified quality metrics over initial price saved an average of $217,000 in net present value over 15 years. That’s not theory. It’s arithmetic.
Homeownership remains the largest wealth-building tool for most Americans—but only when the asset’s fundamentals match the buyer’s timeline, risk tolerance, and usage intent. Cheap properties serve specific strategies: short-hold flips, rental portfolios in high-yield markets, or owner-occupants with renovation expertise. Premium properties serve stability-focused buyers prioritizing health, safety, and predictable equity growth. Neither is universally superior. But understanding the precise, measurable trade-offs transforms guesswork into governance.
For buyers weighing options today: Pull the county assessor’s parcel report, run a free energy audit via ENERGY STAR’s Home Advisor, and compare three recent sales in the exact same subdivision—not the broader ZIP code. The data is public. The discipline is yours.
Remember: A home isn’t just shelter. It’s a financial instrument, a health environment, and a community anchor. Price is the first variable—not the final verdict.
Market conditions shift. Material costs fluctuate. But physics doesn’t lie: R-38 insulation outperforms R-13. Class 4 shingles withstand hail better than 3-tab. And 200-amp panels support tomorrow’s energy needs better than 100-amp relics. Build your decision on what’s proven—not what’s promoted.
Investors who tracked the FHFA House Price Index from 2000–2020 know this well: properties in the top decile by quality-adjusted price index returned 8.4% CAGR—outpacing the S&P 500’s 6.1% over the same period. That edge didn’t come from speculation. It came from specifications.
So measure twice. Choose once. And never let ‘cheap’ distract you from what truly lasts.
Because in real estate, the most expensive thing you can buy is something that fails early, costs more to run, and sells slowly when you need liquidity. The math is clear. The choice is yours.
Whether you’re a first-time buyer in Columbus, OH, a downsizing retiree in Sarasota, FL, or an investor scaling a portfolio in Atlanta, GA—the same principles apply. Quality isn’t a luxury add-on. It’s the foundation of financial resilience.
And resilience, in volatile markets, pays dividends far beyond the balance sheet.
You don’t save money buying cheap. You allocate it—intentionally—to what matters most for your next decade.
That’s not real estate advice. It’s engineering.
And engineering, unlike opinion, is testable, repeatable, and true.